What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Reconcile the records in three stages: match sales invoices and outward supplies to GSTR-1, match purchase records and supplier documents to GSTR-2B, then use the resolved figures to review tax liability and input tax credit (ITC) in GSTR-3B. GSTR-2B is a read-only statement, not a purchase ledger or a final decision on whether credit is eligible.
What each return tells you
- GSTR-1: The statement of outward supplies. It includes invoice-level information for supplies to registered customers and specified interstate B2C invoices, as well as credit and debit notes, exports, advances, amendments, nil, exempt and non-GST supplies, and HSN/SAC summaries. Relevant e-invoice information can be auto-populated into GSTR-1 tables.
- GSTR-2B: A static, read-only statement of inward-supply information from sources including suppliers’ GSTR-1, GSTR-1A and IFF filings, other returns, ISD information and import IGST data from ICEGATE. You cannot add or edit a document in GSTR-2B.
- GSTR-3B: The return in which you report tax liability and ITC. Some values may be auto-populated from GSTR-1/1A and GSTR-2B, but the GST Portal says those values are currently editable. Review the system-computed figures and any manual changes; auto-population does not replace self-assessment.
The GST Portal advises taxpayers to reconcile GSTR-2B with their own records and books. The practical implication is that a portal match is a control, not a substitute for complete accounting records, source documents or checking whether a credit is legally available.
Prepare a period-close workpaper
Choose the tax period and bring together the records needed to explain both what was reported and what remains unresolved. A useful workpaper is an internal control, not a portal-mandated format.
- Sales register and issued invoices; purchase register and supplier invoices.
- Debit notes, credit notes, expense records and import documents, where applicable.
- Prior-period mismatch lists, filed-return copies and payment evidence.
- Separate schedules for outward supplies, inward supplies and ITC, reverse-charge items, and imports.
Use consistent identifiers when matching: GSTIN, invoice or document number and date, supplier or recipient, taxable value, tax amounts, place of supply, document type and accounting/tax period. Keep amendments and notes linked to the documents they change so they are not mistaken for new, unrelated transactions.
Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →#1 Best Overall

- AN EASY & EFFICIENT WAY TO CONTROL YOUR FINANCES: Created for both small business and personal use, this horizontal accounting ledger book has spacious pages to log payments and deposits, so that you can monitor your finances and spot errors easily.
- LARGE FORMAT LEDGER WITH PLENTY OF WRITING SPACE: This accounting book ledger comes in a large format, measures 10 by 7 inches, and has 129 pages with 3,100 entry lines total.
- TRACK ACTIVITY IN MULTIPLE ACCOUNTS WITH JUST ONE BOOK: This accounting log book will be perfect if you want to track activity in multiple accounts. To do so, use the dedicated column to add the bank account number every time you make a record.
- PREMIUM DESIGN FOR COMFORTABLE DAILY USE: This accounting journal book has a durable eco-leather hardcover, thick 120gsm paper, sturdy elastic closure, pen loop, ribbon bookmark, and back pocket for extra notes, checks, and receipts.
- 60-DAY MONEY-BACK GUARANTEE: We will exchange or refund your small business log book if you aren’t satisfied with your business bookkeeping ledger for any reason. Reach out to us via message to refund your monthly accounting ledger book.
Match sales records to GSTR-1
Compare the sales register and issued invoices with the relevant outward-supply details in GSTR-1. Check completeness and classification as well as totals: an invoice can have the correct tax amount but still be reported under the wrong recipient, place of supply, supply category or period.
- Invoice number and date, customer GSTIN and recipient classification.
- Taxable value, tax rate and tax amount, place of supply and supply category.
- Credit and debit notes, amendments, advances and adjustments.
- Exports; nil, exempt and non-GST supplies; and applicable summary tables, including HSN/SAC information.
Investigate sales-book entries missing from GSTR-1, portal entries absent from the sales register, duplicate invoices, incorrect GSTIN or place of supply, period and value differences, and notes or amendments omitted from summaries. First establish which underlying record is wrong, then use the correction route available for the return’s filing status and tax period. Do not assume a filed-period error can always be edited in place.
Rank #2
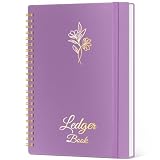
- Refined Financial Management: Our ledger books for bookkeeping can be used to track personal bills and budgets and serve as book keeping log for small business.Helps you keep track of your expenses and income for effective financial planning.
- Adequate Ledger Entries: Dimensions are 8.4 x 6.1 inches, making it easy for you to take anywhere. This accounting ledger comes with 3304 entry spaces (120 pages) so you can record all your financial information in one place, with easier access to track transaction types and dates.
- Elegant & Exquisite Design: Our ledger notebook adopts a classic waterproof material cover, which is not easy to wear. Gold double spiral binding makes flipping through easy. This bookkeeping book is also designed with practical inner pockets and bookmark elastic bands.
- Flexible & Thick Paper: Our accounting book is made of 100gsm non-bleeding paper, perfect for fountain pens, ballpoint pens and other pen types. Convenient to write on, so you no longer have to worry about bleeding ink.
- Perfect For Gift Giving: As you would expect, the cover of the book keeping book is beautifully designed with gold foil lettering and floral patterns. Perfect as a gift for parents and friends, or as a business ledger for small business.
Match purchase records to GSTR-2B
Download and retain the period’s GSTR-2B from the GST Portal; the portal provides the generated statement in Excel or JSON. Match documents individually against the purchase register and supporting supplier invoices rather than relying only on a grand-total comparison.
| Match result | What to investigate | Practical treatment |
|---|---|---|
| In books and in GSTR-2B | Document details, accounting period, notes or amendments, and whether the purchase meets the applicable ITC conditions. | Reconcile the document and assess eligibility independently before reporting credit. |
| In books but not in GSTR-2B | Supplier filing status and timing, recipient GSTIN, invoice identifiers, and whether the document belongs in a later statement. | Record the exception and follow up with the supplier. Do not try to edit the read-only GSTR-2B. |
| In GSTR-2B but not in books | Whether the goods or services were received, whether the invoice is unrecorded, and whether the supplier document is incorrect or duplicated. | Find supporting records, correct the books where appropriate, or investigate the document before deciding on any credit. |
| In both, but details differ | Invoice number/date, taxable value, tax, place of supply, period, and linked credit/debit notes or amendments. | Identify the incorrect source and make the applicable accounting or return correction. |
| Credit note, amendment, import or reverse-charge item | The related source document, original entry and return classification. | Reconcile it to its own support and reflect its treatment in GSTR-3B as applicable. |
Why an invoice date may not match the GSTR-2B period
The supplier’s filing time can affect when a document appears. The GST Portal’s GSTR-2B FAQ describes monthly supplier-filed GSTR-1/1A information as captured across a cutoff window ending on the succeeding month’s 11th, and quarterly/IFF information as captured across a window ending on the 13th. A supplier-filed document appears in the next open recipient GSTR-2B according to the portal’s process, regardless of its issue date. These cutoff descriptions do not guarantee that every document will appear on a particular day or in the period a recipient expects; check the statement and filing circumstances.
The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Rank #3

- Easy To Track Your Finances: HAUTOCO accounting ledger book keeps you on top of your expenses and income! Help you keep your money organized, spend well, and set and achieve financial goals
- Premium Material: The A5 accounting ledger book has a total of 120 pages and 2040 lines of entries. It is made of 100gsm thick paper to reduce ink leakage; it is equipped with a waterproof and sturdy PP cover to protect the inner pages
- Practical Design: Compact 8.3 x 6.2'' expense tracker notebook is easy to carry and features information pages, 2025 calendar, yearly financial goals page, and PVC pocket for storing important tickets and loose items
- Manage Your Finances Effectively: Undated accounting books with number, date, description, account, payment or deposit amount, and total balance. You will be able to easily analyze your financial activities and quickly prepare accurate financial statements
- Ideal For Small Business or Personal Use: An accounting log journal can track your business or personal financial status. With a clear record of transactions, you can find unnecessary expenses or fraudulent charges
Assess exceptions before finalising ITC
Do not treat appearance in GSTR-2B as blanket permission to claim credit. For each proposed credit, confirm supporting documentation and recording, business use, applicable legal eligibility and restrictions for the relevant period, and whether a credit note or required reversal changes the amount. The GST Portal says GSTR-2B marks certain unavailable-credit scenarios, but other legal restrictions may apply and require taxpayer self-assessment.
Use an exception log to keep unresolved items from disappearing at period close. A practical log can record supplier, document, amount or tax difference, period, reason, action owner, supplier follow-up, resolution and the return period in which the correction is reflected. This is a workpaper design suggestion, not a prescribed GST Portal format.
Rank #4

- PU Leather Cover with Gold Foil: Ledger book features a finely textured black pebbled PU leather cover with exquisite gold foil stamping. This not only provides a non-slip, wear-resistant feel but also exudes a luxurious and sophisticated look. The durable material protects the inner pages from damage and is suitable for various scenarios, including business office work and personal finance.
- Portable Size: Columnar book 7 x 9.25 inches, is compact and space-saving, easily fitting into a briefcase, tote bag, or backpack. Whether for business trips, field reconciliation, or everyday carry, it allows for recording income and expenses anytime.
- Large Capacity: Record per book contains 50 sheets of 80g double-sided offset paper. Each page features 30 clear lines of writing and a 3-column categorization layout. Double-sided color printing ensures clear and smudge-proof text. The notebook includes a marker bar for quickly marking important items or reconciliation points. With a total of 1500 writing positions, it meets daily, monthly, and even annual accounting needs, eliminating the need for frequent notebook replacements.
- Eye-friendly Inner Pages: Budget book's inner pages feature a soft, eye-friendly green background with double-sided color printing, effectively reducing visual stimulation from strong light reflection. This minimizes eye fatigue even during extended writing sessions, reflecting a healthy and thoughtful design consideration, making it suitable for those who frequently keep track of their expenses.
- Comfortable Writing Experience: Logs book's spacious line spacing provides ample space for writing, allowing for clear categorization of income, expenses, and balances, resulting in more organized budgeting. It also ensures clear and neat handwriting, enhancing writing fluency and overall page neatness.
Tie the resolved figures to GSTR-3B and payment
After resolving the sales and purchase matches, review GSTR-3B against the books and the relevant filed outward-supply data. Check that liability is complete, including reverse-charge liability; that reverse-charge tax is paid; and that eligible ITC, required reversals and ineligible amounts are classified in the appropriate fields. Compare system-generated figures with your reconciled schedules and investigate each manual edit instead of accepting or changing auto-populated values without support.
The GST Portal specifically cautions taxpayers not to avail the same document’s credit twice, to reverse credit as required by the GST Act and Rules, and to pay reverse-charge tax. Its statement may not flag every legal restriction on ITC, so a clean match alone is not an eligibility conclusion.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Repair Windows errors before they cause bigger problems3Scan for outdated or missing drivers - takes under a minuteBest Value
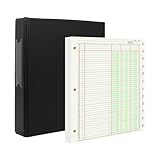
- [A Value Set]: Our Accounting Ledger Paper notebook comes with 100 sheets/200 pages ledger papers and a PU leather 3 ring binder. Extra Movable Monthly Tabs
- Thick Paper: These 3 column ledger paper are 100 gsm, Can be written smoothly to prevent ink bleeding. Both sides can be used
- [Size]: The size of the columnar pad paper is 8.5" X 11". The black 3-ring binder can be used for 8.5X11 refill paper
- [3-Ring Binder & Movable Monthly Tabs]: Binder accounting ledger notebook can be added, deleted, and re-arranged pages easily. The month tabs make it easy to organize the same months from different years
- Application: The ledger paper notebook is perfect for bookkeeping, accounting or other numeric data. it can be used by accountants, teachers, student
Use the mismatch to choose the next action
| Mismatch | First checks | Next action |
|---|---|---|
| Sales-book invoice absent from GSTR-1 | Filing completeness, GSTIN, invoice period, supply classification and whether the return is draft or filed. | Correct through the process available for that return status; check the summary and filed copy. |
| Purchase invoice absent from GSTR-2B | Supplier filing and cutoff timing, recipient GSTIN, invoice identifiers and the next open statement. | Follow up with the supplier and track the exception; GSTR-2B itself cannot be edited. |
| GSTR-2B invoice absent from books | Receipt and purchase records, duplicate or incorrect supplier reporting, and possible accounting omission. | Locate support, correct the books or dispute the document, and assess eligibility on the facts. |
| Taxable value or tax differs | Invoice, note or amendment, rate, tax category, place of supply and period. | Determine which record is wrong and apply the relevant accounting or return correction. |
| Credit may be duplicated or reversed | Original and amended documents, notes, prior claims and reversal entries. | Prevent duplicate availment and make any required reversal in the appropriate period. |
| Reverse-charge supply does not tie out | Contract and invoice classification, tax payment, and any related ITC eligibility. | Report and pay reverse-charge liability; claim related credit only if eligible. |
Correct errors with the right period and filing status in mind
The GST Portal describes GSTR-1A as an optional facility to add or amend same-period details after GSTR-1 is filed or its due date has passed, whichever is later, and before filing GSTR-3B for that period. Changes flow into that same-period GSTR-3B. Supplier changes in GSTR-1A are reflected in the recipient’s GSTR-2B for the next tax period. Confirm current portal behavior and applicable law before relying on this route; it is not a general way to edit any previously filed return.
The portal FAQ lists monthly GSTR-1 as due on the 11th day of the succeeding month and quarterly GSTR-1 on the 13th day after the quarter. It also gives 30 November of the following financial year as the cutoff for amending prior-financial-year invoice details. These are portal-stated procedural dates, subject to government notifications and changes in law. Verify the due date and correction limit for the specific return period rather than treating these dates as universally current.
Retain a trail that explains the filed return
Keep filed returns, downloaded GSTR-2B statements, ledgers, invoice and note support, payment evidence and reconciliation workpapers under the applicable record-retention rules. Carry unresolved mismatches forward with their status and revisit them when supplier filing, a correction or further documentation arrives. The required retention period and treatment depend on current law and the taxpayer’s circumstances.
For a fact-specific ITC, accounting or disputed-transaction decision, check the applicable CGST/IGST law, rules and notifications or consult a qualified tax professional. Portal guidance explains how return data is handled; it does not determine every taxpayer’s legal entitlement.
Free tools Windows power users keep installed
One-click scans. No signup required.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.